
Set up a company in Dubai: Free Zone does not automatically mean 0% tax.
Dubai and the UAE remain among the world’s most competitive business hubs. Corporate Tax changed the planning question: it is no longer simply “Free Zone or Mainland?”, but what you do, who you trade with, what income you earn, where substance sits and where you personally remain tax resident.
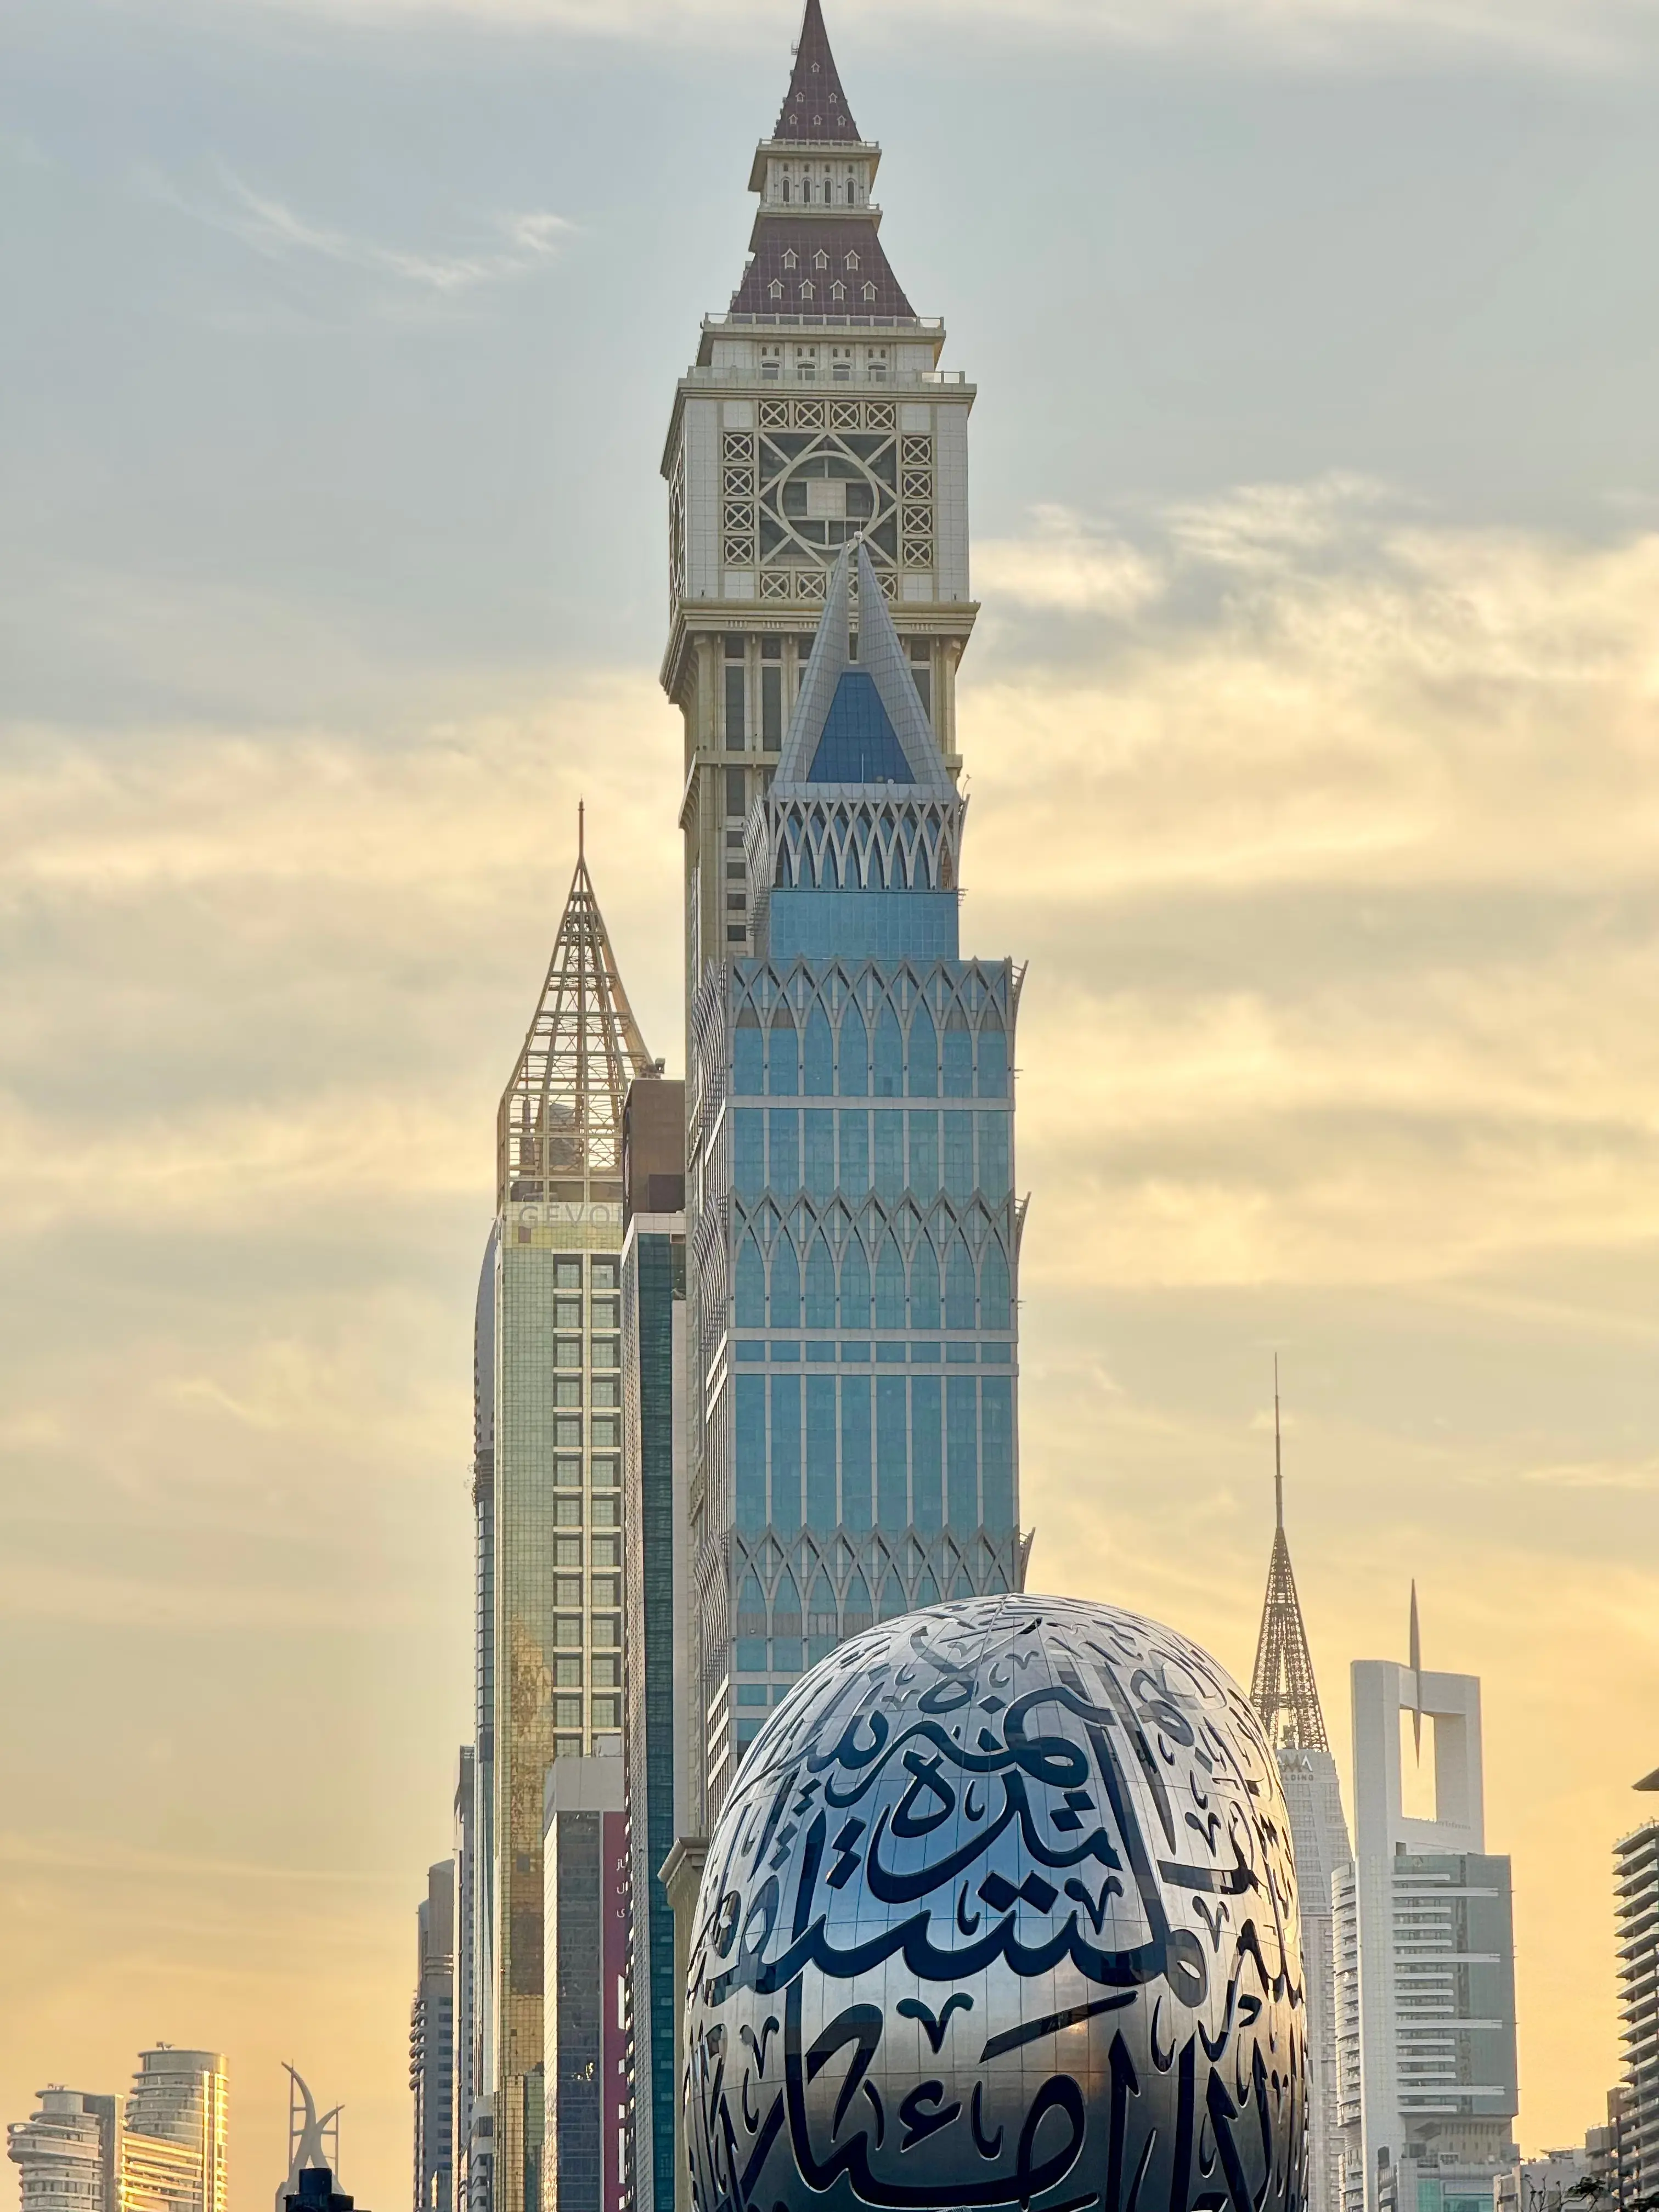
Dubai remains highly competitive. The structure matters more now.
A UAE company sits within the federal Corporate Tax regime. Ordinary companies generally pay 0% on the first AED 375,000 of taxable income and 9% above that amount. A Free Zone Person is also within Corporate Tax; only a Qualifying Free Zone Person (QFZP) meeting all conditions can access 0% on Qualifying Income.
Local operating flexibility
Can suit businesses focused on the UAE market. Up to 100% foreign ownership is available for most activities, subject to strategic-sector restrictions.
Specialised ecosystem
Can streamline setup and international business. The tax result depends on QFZP status, activity, counterparties, substance and income type.
The licence is one layer
Founder residence, banking, visa, effective management, team, office and dividend flows can matter more than the initial setup fee.
“Free Zone always means 0%.”
“Foreign customers automatically create Qualifying Income.”
“A flexi-desk automatically satisfies substance.”
“If the company is in Dubai, my home country cannot tax it.”
QFZP requires continuous compliance with statutory conditions.
Qualifying and Excluded Activities are defined and were updated in 2025.
QFZP requires adequate substance, arm’s length, transfer pricing and audited financials.
A home country can still treat a foreign company as resident where effective management sits there.
Free Zone 0% comes with conditions, limits and compliance cost.
To remain a QFZP, the company must carry out core income-generating activities in the Free Zone, maintain adequate assets, qualified employees and operating expenditure, derive Qualifying Income, comply with transfer pricing, maintain audited financial statements and meet de minimis.
Core income-generating activities performed in the Free Zone.
Adequate assets, qualified employees and operating expenditure.
Non-qualifying revenue within the lower of 5% of total revenue or AED 5,000,000.
Loss of QFZP status can affect the relevant period and the following four periods.
Non-qualifying taxable income of a QFZP is taxed at 9%; do not assume the ordinary AED 375,000 band applies.
Low tax does not mean low compliance.
| Area | 2026 rule | What we review |
|---|---|---|
| Corporate Tax | All taxable juridical persons must register. Entities incorporated from 1 March 2024 generally register within 3 months. | Registration, tax period, return and payment. |
| Tax Return | Return and payment are generally due within 9 months after the Tax Period ends. | Annual compliance calendar. |
| QFZP | 0% only on Qualifying Income; 9% on non-qualifying taxable income. | Activity, counterparty, PE, IP, real estate and de minimis. |
| Audit | QFZP must maintain audited financial statements even below AED 50M revenue. | UAE auditor and close process. |
| VAT | 5% standard rate. UAE-resident businesses generally face mandatory registration above AED 375,000; voluntary threshold AED 187,500. | Place of supply, exports, reverse charge and registration. |
| Transfer Pricing | QFZPs must comply with arm’s-length and applicable documentation rules. | Owner/group transactions and related parties. |
| Licence | The licensed activity and authority should match the real business. | Scope, approvals and renewal. |
| Banking / KYC | A licence and Emirates ID do not guarantee a corporate account. | Business model, clients, UBO, source of funds and substance. |
Free Zone point: the 0% rate is a tax regime with ongoing conditions, not a licence feature.
International/B2B consulting where the operating model fits the selected regime.
Holding, headquarters, treasury, logistics, distribution or other properly structured qualifying activities.
Business with real team, office and management in UAE.
Founder who also makes a defensible personal tax-residence move to UAE.
Owner living in and managing everything from another country with no real UAE substance.
Free Zone selected only because a formation agent promised “guaranteed 0%”.
B2C or excluded activity without modelling actual tax treatment.
Plan dependent on banking or visa before KYC/immigration approval.
A Dubai company can be UAE-incorporated and still create home-country tax exposure.
For example, Spanish law treats a company as Spanish tax resident if its place of effective management is in Spain, meaning the direction and control of its overall activities are carried out there. A UAE licence, registered office or bank account does not by itself solve that issue.
Spain and the UAE have a double tax treaty in force since 2 April 2007. Treaty protection can help with specific conflicts, but it does not replace coherent facts and substance.
The UAE does not levy personal income tax on individuals. That matters only if the founder genuinely exits their former tax residence and satisfies the relevant residence rules.
See Dubai/UAE tax residencySee Spain departure planning
Company, residence and tax should be designed together.
N30 Global starts with the business model and founder residence before choosing the licence.
Explore International Tax TailoringMap activity and clients: B2B/B2C, countries, services, IP, e-commerce, holding.
Choose Mainland vs Free Zone and licensing authority.
Model Corporate Tax: QFZP, Qualifying Income, substance, PE and transfer pricing.
Coordinate founder residence, visa, housing and departure-country position.
Plan banking/KYC, bookkeeping, VAT and annual compliance.
Implement only when the overall structure is defensible.
Dubai company formation: questions to answer before paying for a licence.
Does a Dubai Free Zone company automatically pay 0% Corporate Tax?
No. A QFZP can access 0% on Qualifying Income only if all statutory conditions are met. Non-qualifying taxable income is subject to 9%.
What is the general UAE Corporate Tax rate?
For an ordinary taxable company, 0% applies to the first AED 375,000 of taxable income and 9% above that threshold.
What is a QFZP?
A Free Zone Person satisfying conditions including adequate substance, Qualifying Income, arm’s-length/transfer-pricing compliance, audited financial statements and de minimis.
How much non-qualifying revenue can a QFZP have?
Generally, non-qualifying revenue must remain within the lower of 5% of total revenue or AED 5,000,000, subject to specific calculation rules.
Free Zone or Mainland?
It depends on activity, market access, counterparties, licence, office, visa, Corporate Tax and substance. There is no universal best route.
Can a foreigner own 100% of a Mainland company?
For most commercial activities, 100% foreign ownership is available, while strategic/restricted activities can have different rules.
Is there VAT in the UAE?
Yes. The standard rate is 5%. UAE-resident businesses generally face mandatory registration once taxable supplies/imports exceed AED 375,000.
Does a QFZP need audited financial statements?
Yes. QFZPs are required to prepare and maintain audited financial statements for Corporate Tax purposes.
Can I manage my Dubai company from Spain or another country?
You can own it, but effective management from another country can create corporate-residence, PE, CFC or other tax exposure there.
Does a Dubai company automatically give me personal tax residence?
No. Company licensing, immigration residence/visa and personal tax residence are separate concepts.
Current UAE rules, not old “Free Zone = 0%” content.
Technical review: 6 September 2026.
You do not need “a Free Zone”. You need the UAE structure that fits your business and your residence.
We compare Mainland, Free Zone, Corporate Tax, QFZP, visa, banking and departure-country exposure before formation, so a cheap setup does not become an expensive mistake.
Own Your Money.
General information only. Not individual UAE, Spanish or international tax/legal advice.