
European Union, Mediterranean lifestyle and one of the more compelling personal tax frameworks for international founders, investors and professionals. Cyprus can offer tax residency under the 60-day rule when every condition is met, alongside a non-dom regime that is particularly relevant for dividends and interest.
A European tax base built for internationally mobile profiles.
Cyprus stands out because the proposition is not built around one headline rate. It combines flexible tax residency, non-dom, an EU company environment, widely used business English and a Mediterranean lifestyle that can support a genuine move.
| Factor | Cyprus 2026 | What it means for you |
|---|---|---|
| Tax residency | More-than-183-day rule or alternative 60-day rule where all conditions are met. | Can provide a much more mobile EU residency model than the classic 183-day approach. |
| 60-day rule | ≥60 days in Cyprus, no >183 days in any other country, Cyprus business/employment/directorship and a permanent home owned or rented. | It is not an automatic “60-day residence”: genuine economic and residential ties are required. |
| Non-dom | A Cyprus tax resident who qualifies as non-domiciled is outside Special Defence Contribution on dividends and interest. | Highly relevant for shareholders and investors with passive income, although non-dom does not remove every Cyprus tax or contribution. |
| Non-dom duration | Deemed domicile generally arises after being Cyprus tax resident for at least 17 of the previous 20 years. | A long-duration advantage, but not an indefinite exemption. |
| Personal income tax 2026 | 0% to €22,000, then progressive bands up to 35% on taxable income above €72,000. | The strongest case often comes from how non-dom, salary, dividends and structure interact rather than from a flat income-tax rate. |
| Qualifying employment | Certain new employees may claim a 50% exemption on employment remuneration for up to 17 years when the Article 8(23A) conditions are met. | Can make Cyprus highly competitive for executives and founders receiving genuine Cyprus employment income. |
| Cyprus company | 15% general Corporate Income Tax from 1 January 2026. | Still competitive, but the pre-2026 12.5% headline rate should no longer be used. |
General information reviewed in September 2026. Effective taxation depends on income mix, domicile, previous residence, employment, companies, applicable contributions and the relevant tax treaty.
It is not a “zero-tax paradise”. It is something more useful: a system that can fit very well.
Non-dom
The SDC exemption on dividends and interest can be particularly valuable for shareholders, investors and internationally diversified wealth profiles.
60-day rule
Where every condition is satisfied, Cyprus offers considerably more physical-presence flexibility than many traditional European tax residencies.
Inside the EU
Euro, EU legal framework and a business jurisdiction that feels familiar to European customers, banks and professional counterparties.
Mediterranean business base
Limassol combines sea, housing, professional services and an international community large enough to support genuine residence and business substance.
Cyprus is one of the few places where EU access, lifestyle and international tax planning can reinforce each other.
183 days or 60 days. The second test is about more than flight counts.
Important 2026 change: the old condition requiring the individual not to be tax resident in any other state was removed from the 60-day rule.
That does not make dual residence irrelevant. If another country also treats you as resident, domestic law and, where available, treaty tie-breaker rules still need to be analysed.
Non-dom: the key question is what income you actually receive.
Non-dom does not make every category of income exempt. Its core value is that a Cyprus tax resident who is non-domiciled is exempt from Special Defence Contribution on dividends and interest.
That can be extremely valuable for shareholders and investors, while being much less decisive for someone whose main income is ordinary salary or professional earnings.
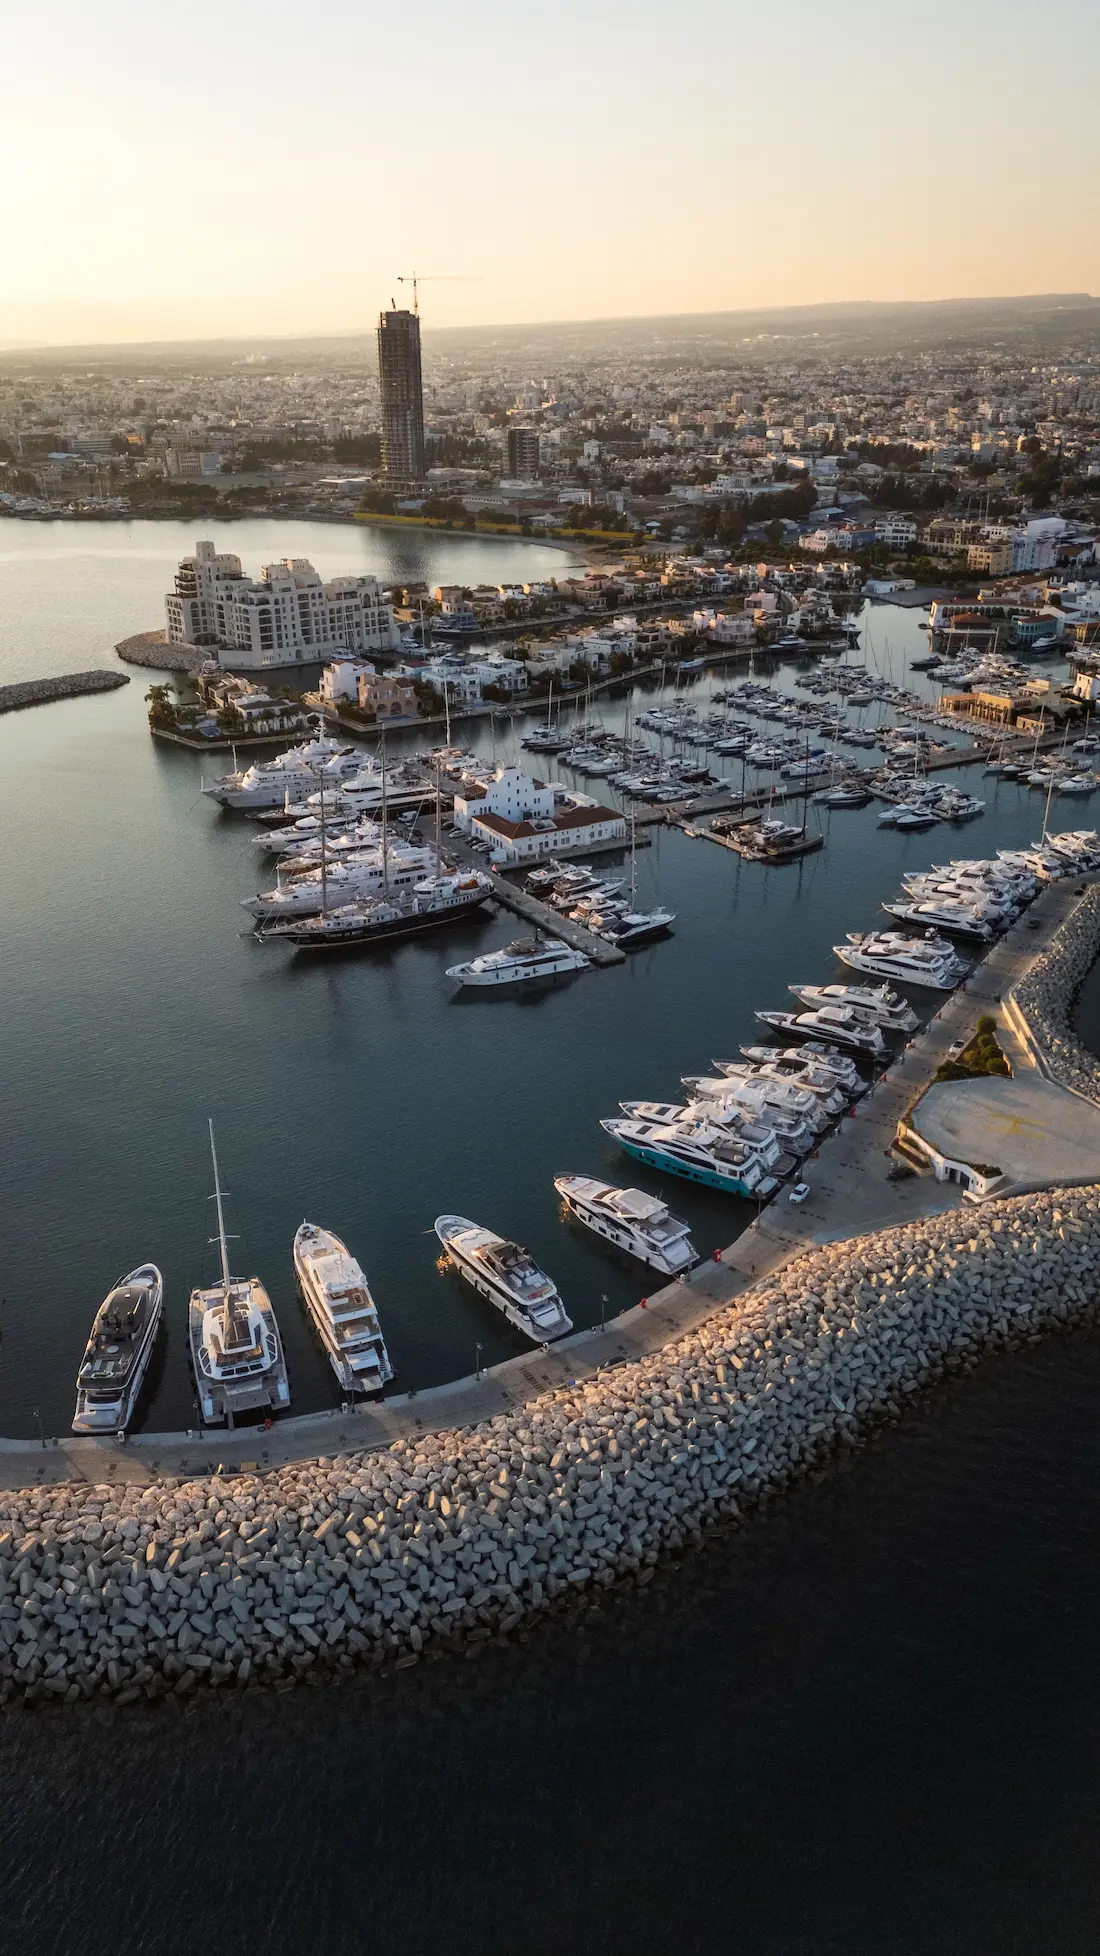
Sea, city, euro and business. Limassol makes the proposition easy to picture.
For many founders and families, Cyprus works because tax residency can coexist with a genuine daily life: Mediterranean housing, professional services, international schools, flight connections and an established international business community.
60 days ≠ tax tourism
The test requires a permanent home and genuine economic or professional ties to Cyprus.
→Tax residency ≠ immigration permission
Administrative residence depends on nationality and status and must be coordinated separately.
→Company ≠ universal requirement
It can provide the relevant tie and operating platform, but only where it has genuine economic purpose.
→From tax rules to real life
The question is not “can I do 60 days?”. It is “can I build a complete case that makes sense?”.
N30 Global coordinates tax residency, non-dom, housing, company, remuneration, departure from the previous country and evidence so that every part supports the others.
Assess
Income, dividends, business, employment, wealth, family, mobility and current residence.
Model
183 vs 60 days, non-dom, salary, dividends, company and departure-country scenario.
Prepare
Housing, office/employment/business tie, documents, tax registration and evidence.
Coordinate
Local professionals, administrative residence, company where relevant and roadmap execution.
We do not sell “60 days in Cyprus”. We design a residency you can evidence and maintain.
Cyprus can be flexible. Your departure from Spain still needs to be real.
Cyprus tax residency: the questions that separate structure from headlines.
The 60-day rule and non-dom regime are attractive because they are specific. Understanding the conditions is what makes the strategy useful.
Can I become Cyprus tax resident by spending only 60 days there?
What changed in the 60-day rule in 2026?
What does Cyprus non-dom status mean?
How long can non-dom status last?
What are Cyprus personal income tax rates in 2026?
Is there a 50% exemption for new employees?
Do I need a Cyprus company?
Can N30 Global coordinate implementation?
If you want Europe without giving up competitive international tax planning, Cyprus belongs on the shortlist.
We assess your income, business, dividends, mobility and departure country to determine whether the 60-day rule and non-dom regime genuinely improve your position. If they do, we design the roadmap and can coordinate implementation.
60 minutes · Private · No obligation
Own Your Money.